Black background with scattered dark grey outlined circles of varying sizes.

Trusted by our
leading partners:

Halifax logo with white text and geometric shapes on a blue background.NatWest logo with three red cubes forming a triangle above the white text on a purple background.Nationwide logo with red abstract house icon on dark blue background.HSBC logo with black letters and a red and white hexagon symbol above.Virgin Money logo with red text on a black background.Barclays bank logo with a white eagle icon above the word BARCLAYS on a blue background.White bold letters spelling GEN H with a red house-shaped icon under the E on a black background.Logo for The Mortgage Works with orange text and a star symbol.BM Solutions logo with text from Birmingham Midshires.Aldermore logo with a yellow dot replacing the letter o.Kensington brand logo with stylized white letter K on black background.Paragon text logo with a green and black abstract bird shape above the letter g.Bluestone logo with blue and gray text and a blue sphere at the end.Buildloan logo with a stylized roof over the letter 'l' in the word loan.Coutts logo with stylized text and three crowns icon separated by a vertical line.

First-time buyers

Buying your first property in Thurrock is an exciting financial milestone, but handling deposit requirements, Agreement in Principle documents, and legal checks can feel overwhelming. We take the stress out of entering the Thurrock market by calculating your precise borrowing capacity 3 to 6 months before you begin viewing properties, preventing you from wasting time on homes outside your budget. We guide you through available deposit boost options, Joint Borrower Sole Proprietor (JBSP) agreements, and family gifted deposit rules. Once you find the right Thurrock property, we handle the application process through to completion.

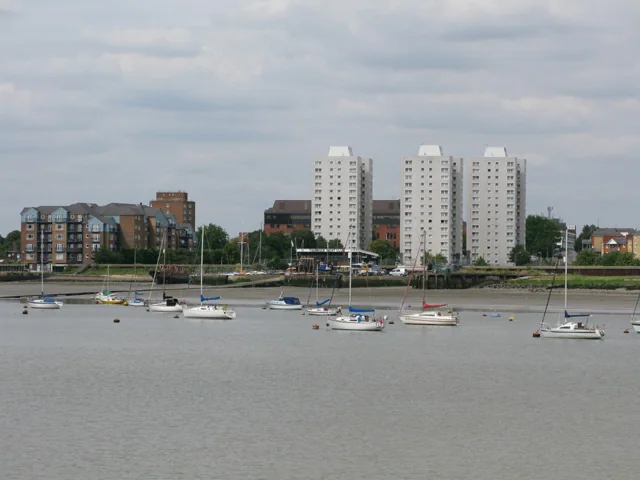
Boats moored on the Thames with flats and tower blocks along the Grays riverside
More on first-time buyer mortgages

Moving home

Relocating within Thurrock or moving into the borough requires managing an outgoing sale and an incoming purchase simultaneously, making timing and organisation vital. We evaluate your current mortgage deal to decide whether porting your existing interest rate to your new Thurrock property makes financial sense compared to switching to a new lender, taking into account any potential Early Repayment Charges (ERCs). Our team calculates your total moving expenses, establishes your maximum purchasing budget, and keeps conveyancers on schedule to avoid chain delays.

Boats moored on the Thames with flats and tower blocks along the Grays riverside
More on moving home mortgages

Remortgaging and rate switches

Remaining on your current lender's Standard Variable Rate (SVR) after a fixed product finishes can add hundreds of pounds to your monthly household budget. For homeowners across Thurrock, we recommend starting the remortgage process 6 months prior to your fixed rate expiration date. This allows us to lock in a competitive benchmark rate early as protection against interest rate increases, while retaining full flexibility to switch to a lower rate if market conditions improve before completion. We compare your current lender's retention offers against the wider market to ensure your home remains cost-effective.

Boats moored on the Thames with flats and tower blocks along the Grays riverside
More on remortgaging

Self-employed mortgages

If you run a local business, work as a sole trader, or trade as a company director in Thurrock, high street lenders often apply rigid automated rules. Lenders assess self-employed income in fundamentally different ways: some average two full years of trading accounts, others assess solely the latest trading year, and select lenders calculate affordability using your salary plus your share of retained business profits. As local mortgage advisers, we know which lenders evaluate your type of trading setup favourably, ensuring your application reaches underwriters who assess your accounts accurately.

Boats moored on the Thames with flats and tower blocks along the Grays riverside
More on self-employed mortgages

Buy-to-let and portfolio landlords

Navigating the Thurrock private rental market requires specialist mortgage advice, particularly with shifting regulatory standards and strict rental yield stress testing. Whether you are purchasing your first buy-to-let flat near Lakeside or expanding an established residential portfolio across Thurrock, we help you evaluate borrowing as an individual versus using a Limited Company / Special Purpose Vehicle (SPV) structure for tax efficiency. For landlords with four or more mortgaged properties, we package your entire portfolio professionally for specialist lenders who underwrite your holdings as a commercial business.

Boats moored on the Thames with flats and tower blocks along the Grays riverside
More on buy-to-let mortgages

Adverse and bad credit mortgages

A past credit issue does not automatically mean you cannot buy or remortgage a home in Thurrock. Lenders judge historical defaults, old CCJs, missed credit payments, or completed debt management plans in vastly different ways depending on their recency, value, and context. Rather than risking a credit decline on the high street, our team examines your full credit report upfront, matches you with adverse-credit lenders who review cases manually, and gives you clear advice on whether applying now or waiting a short period will secure a cheaper rate.

Boats moored on the Thames with flats and tower blocks along the Grays riverside
More on adverse credit mortgages

High net worth and complex income mortgages

Standard automated affordability calculators frequently fail high earners looking to purchase higher-value properties in premium locations like Orsett Village, Horndon-on-the-Hill, or Chafford Hundred. If your remuneration includes variable performance bonuses, complex dividend distributions, foreign currency income, or wealth held in assets rather than traditional salary, high street algorithms often cannot read your profile accurately. We deal directly with specialist lenders and bespoke underwriting desks that manually assess complex financial profiles, constructing custom high-value mortgage structures tailored to your wider financial goals.

Boats moored on the Thames with flats and tower blocks along the Grays riverside
More on high net worth mortgages
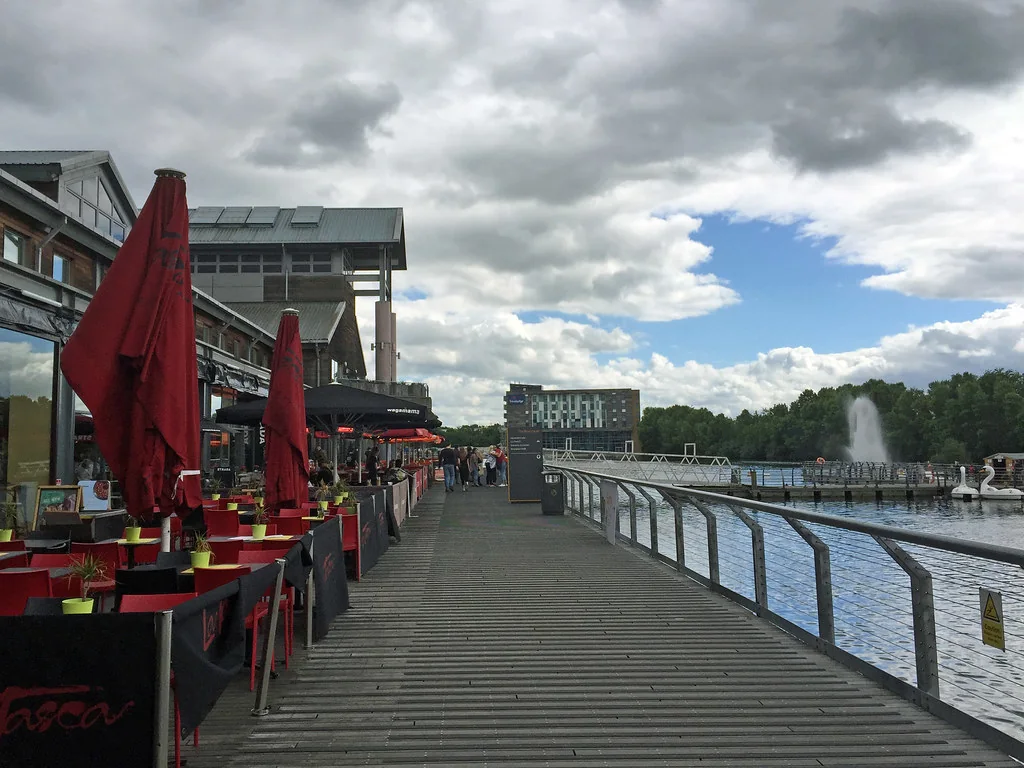
Waterside boardwalk with restaurant seating and a fountain in the lake at Lakeside

Why work with a local mortgage broker

Thurrock covers very different places, from Grays and Tilbury on the river to Chafford Hundred, South Ockendon and Aveley in the west and Stanford-le-Hope, Corringham, Orsett and Horndon-on-the-Hill to the east. The borough has seven conservation areas, including the Bata estate in East Tilbury, and Thurrock Council is a unitary authority, so there is no separate county charge.

That spread shows up in lending. Post-war estates can include non-standard construction, many Bata houses are listed, and village homes can come with private drainage or conservation rules. We check the property as well as the numbers before an application goes in.

We offer full flexibility for client consultations, welcoming you for face-to-face meetings, or conducting phone reviews and video calls to suit your routine. From checking your initial bank statements to communicating with local estate agents and solicitors, our team handles the behind-the-scenes administration so your transaction moves forward smoothly.

How to apply

Getting expert mortgage advice in Thurrock is straightforward, transparent, and completely tailored to your schedule. Whether you have a quick question about your deposit or need a full review of your borrowing potential, reaching out carries zero obligation. We guide you through the process from your very first conversation right through to completion day in three clear steps:

1. First contact and affordability assessment

Reach out by calling our local team on 0333 339 0440 or sending us a message online. We will arrange an initial, no-obligation consultation at a time that suits you: in person, over the phone, or via video link. During this conversation, we review your financial picture, assess what you can realistically borrow, and confirm how much deposit or equity you have available.

2. Searching lenders and handling your application

Your dedicated adviser searches across an extensive panel of UK lenders to locate the most suitable mortgage rate for your circumstances. Once you are happy to move forward, we prepare and submit your full application. We gather your paperwork, submit income evidence, and deal directly with lender underwriters to ensure your Agreement in Principle moves smoothly to a formal mortgage offer.

3. Managing the chain through to completion

Our work does not end when your mortgage offer is approved. We stay actively involved right up until completion day, communicating with local Thurrock estate agents, surveyors, and conveyancers on your behalf. We proactively solve administrative hurdles or chain delays so that your funds reach your solicitor smoothly on completion day.

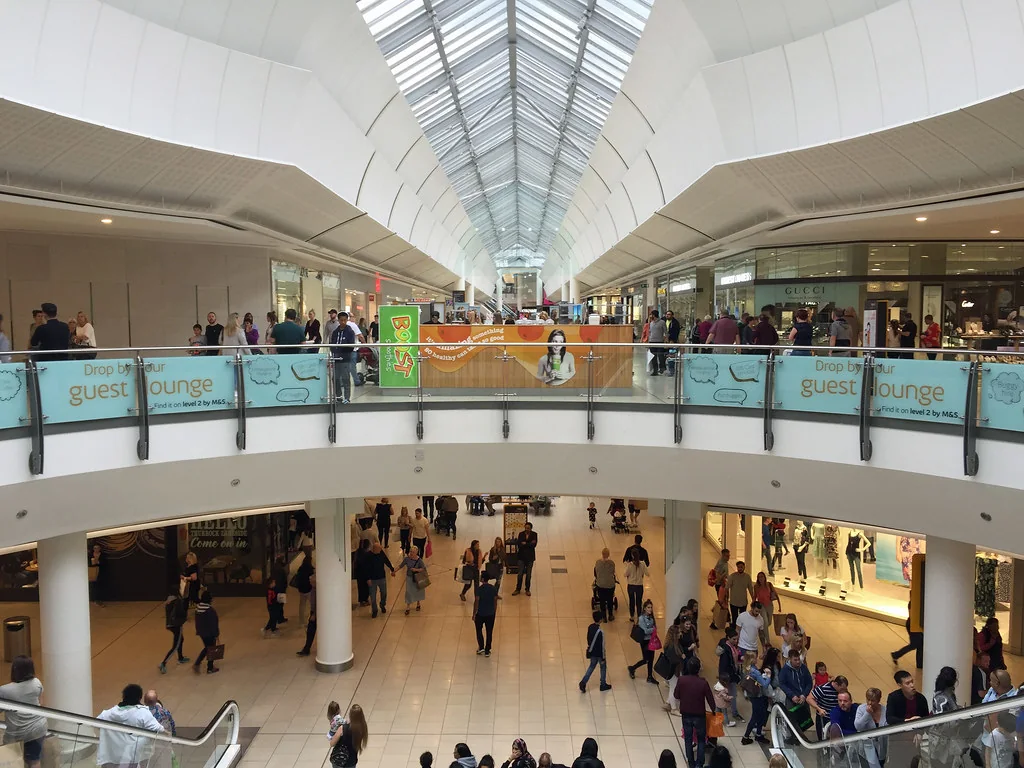
Shoppers on two levels under the glass roof inside Lakeside Shopping Centre

If you are ready to take your next step on the Thurrock property ladder, protect your household against rising interest rates, or release equity from your current home, speaking to an adviser before committing to a deal is invaluable.

When you contact AB Mortgages, your initial consultation is completely free with no obligation to proceed. You will speak directly to a qualified local adviser who will calculate your exact borrowing power and guide you towards suitable mortgage options for your budget. There may be a fee for mortgage advice. The precise amount depends on your circumstances and will be agreed upon before proceeding.

Take the first step today by calling our team on 0333 339 0440 to speak with an adviser.

Your home may be repossessed if you do not keep up repayments on your mortgage.

You may have to pay an early repayment charge to your existing lender if you remortgage.

Not all Buy to Let Mortgages are regulated by The Financial Conduct Authority.

Thurrock

The map will load once you allow functional cookies.

What is the council tax Band D rate for Thurrock Council residents?

Thurrock is governed by Thurrock Council, a unitary authority. For the 2026/27 financial year, the baseline Band D council tax charge across Thurrock is £2,254.68 per year. This total includes funding for core council services alongside statutory precepts collected for Essex Police and Essex Fire & Rescue.

What are official average house prices across property types in Thurrock?

ONS and HM Land Registry figures put the provisional average price in Thurrock at £322,000 in July 2026. By property type, flats and maisonettes averaged £189,000, terraced houses £319,000, semi-detached £401,000 and detached £596,000.

What are the average purchase figures for first-time buyers and mortgaged purchases in Thurrock?

ONS figures show first-time buyers in Thurrock paid an average of £296,000 in July 2026. For homes bought with a mortgage across all buyer types, the average price was £324,000.

How fast is the c2c train journey from Thurrock stations to central London?

Thurrock is served by multiple stations on the c2c rail network, including Chafford Hundred, Grays, Ockendon, Purfleet-on-Thames, Stanford-le-Hope, and Tilbury Town. Direct peak commuter services reach London Fenchurch Street in approximately 33 to 45 minutes depending on your departure station.

What role do major Thames Gateway infrastructure projects play in Thurrock's property market?

Thurrock is home to major national logistics and commercial infrastructure hubs, including DP World London Gateway, the Port of Tilbury, and the Lakeside regional shopping complex. These major industrial and commercial projects generate high demand for local rental homes and starter properties from logistics, trade, and retail professionals.

Are there specialist mortgage requirements for timber-framed or non-standard homes in Thurrock?

Yes. Certain residential areas across Thurrock (including older post-war housing in South Ockendon or Tilbury) feature non-standard construction methods, such as concrete panel framing or timber frames. Mainstream lenders review structural surveys carefully, but we match buyers with lenders experienced in underwriting non-standard construction stock.

How much private rental income do landlords achieve across Thurrock?

ONS figures show average private rents in Thurrock were £1,380 a month in August 2026. One-bedroom homes averaged £941, two-bedroom £1,214, three-bedroom £1,474 and four-bedroom or larger £2,195.

Figures correct as at September 2026, based on ONS House Price Index figures for July 2026 (provisional) and ONS private rent figures for August 2026.

What deposit level do first-time buyers need to enter the Thurrock property market?

With average first-time buyer prices in Thurrock standing around £296,000, a 5% deposit equals £14,800 under high-LTV schemes. Putting down a 10% deposit (£29,600) unlocks access to significantly reduced interest rate tiers across mainstream and regional lenders.

What outdoor parks and countryside amenities are located across Thurrock?

Thurrock offers extensive green spaces and nature reserves, including Belhus Woods Country Park in Aveley, Thameside Nature Discovery Park in Mucking, Chafford Gorges Nature Park, and the historic grounds around Coalhouse Fort in East Tilbury.

When should I obtain an Agreement in Principle before viewing homes in Thurrock?

We recommend speaking to a broker 3 to 6 months before you start viewing, then getting your Agreement in Principle (AIP) shortly before you begin, as an AIP is only valid for a limited period. Local Thurrock estate agents routinely request verified AIP documentation before presenting formal purchase offers to sellers, giving your offer immediate standing.

Whatsapp svg icon