Black background with scattered dark grey outlined circles of varying sizes.

Trusted by our
leading partners:

Halifax logo with white text and geometric shapes on a blue background.NatWest logo with three red cubes forming a triangle above the white text on a purple background.Nationwide logo with red abstract house icon on dark blue background.HSBC logo with black letters and a red and white hexagon symbol above.Virgin Money logo with red text on a black background.Barclays bank logo with a white eagle icon above the word BARCLAYS on a blue background.White bold letters spelling GEN H with a red house-shaped icon under the E on a black background.Logo for The Mortgage Works with orange text and a star symbol.BM Solutions logo with text from Birmingham Midshires.Aldermore logo with a yellow dot replacing the letter o.Kensington brand logo with stylized white letter K on black background.Paragon text logo with a green and black abstract bird shape above the letter g.Bluestone logo with blue and gray text and a blue sphere at the end.Buildloan logo with a stylized roof over the letter 'l' in the word loan.Coutts logo with stylized text and three crowns icon separated by a vertical line.

First-time buyers

Buying your first home in Stanford-le-Hope can involve much more than finding a suitable property. You need to understand how much you can borrow, what deposit is realistic, how lenders will assess your income, and which costs need to be allowed for alongside the purchase price. We can review your finances before you begin viewing, arrange an Agreement in Principle when appropriate, explain gifted deposits and Joint Borrower Sole Proprietor arrangements, and help you understand the differences between mortgage products. Once you have an offer accepted, we prepare the application and manage lender queries through to mortgage offer and completion.

Lake edged with reeds and trees near Stanford-le-Hope under a cloudy sky
More on first-time buyer mortgages

Moving home

Moving within Stanford-le-Hope, relocating from another part of Essex, or buying into the area while selling your existing property means coordinating several financial and legal steps at the same time. We review your current mortgage to establish whether it can be ported, whether Early Repayment Charges apply, and whether changing lender could be more suitable. We also calculate the borrowing required for the new purchase, factor in available equity and moving costs, and work alongside your estate agent and conveyancer so the mortgage side of the chain remains organised.

Lake edged with reeds and trees near Stanford-le-Hope under a cloudy sky
More on moving home mortgages

Remortgaging and rate switches

If your current fixed or discounted mortgage deal is approaching its end, reviewing your options early can reduce the risk of moving automatically onto your lender's Standard Variable Rate. For homeowners in Stanford-le-Hope, we can start assessing the market several months before the existing product expires. We compare product-transfer options from your current lender with suitable remortgage products elsewhere, taking account of fees, incentives, Early Repayment Charges, loan-to-value, and the total cost over the relevant period rather than focusing only on the headline rate.

Lake edged with reeds and trees near Stanford-le-Hope under a cloudy sky
More on remortgaging

Self-employed mortgages

Stanford-le-Hope and the wider Thurrock area are home to many contractors, sole traders, limited-company directors, and owners of established local businesses. Mortgage lenders do not all assess self-employed income in the same way. Some use an average of recent trading years, some can use the latest year where income is rising, and certain lenders may consider a director's salary together with their share of company profits. We review the accounts, tax calculations, business structure, and income pattern before recommending a lender whose underwriting approach is appropriate for the case.

Lake edged with reeds and trees near Stanford-le-Hope under a cloudy sky
More on self-employed mortgages

Buy-to-let and portfolio landlords

Stanford-le-Hope's rail connection, access to the A13, and range of housing make the wider SS17 area relevant to landlords as well as owner-occupiers. Buy-to-let applications are assessed differently from residential mortgages, with rental income, stress testing, deposit level, property type, and the applicant's wider portfolio all potentially affecting the outcome. We advise first-time landlords and experienced portfolio investors, including clients considering Limited Company or Special Purpose Vehicle structures. Tax treatment is a separate area, so we recommend taking appropriate tax advice before deciding how a property should be owned.

Lake edged with reeds and trees near Stanford-le-Hope under a cloudy sky
More on buy-to-let mortgages

Adverse and bad credit mortgages

A missed payment, default, CCJ, historic debt arrangement, or other credit issue does not automatically prevent someone from obtaining a mortgage in Stanford-le-Hope. The important details are usually what happened, how long ago it occurred, the amount involved, whether it has been satisfied, and how the rest of the application looks today. We review your credit history before an application is submitted and consider lenders whose criteria match the circumstances. Where waiting could materially improve the options available, we will explain that rather than pushing ahead with an unsuitable application.

Lake edged with reeds and trees near Stanford-le-Hope under a cloudy sky
More on adverse credit mortgages

High net worth and complex income mortgages

Not every Stanford-le-Hope mortgage fits a standard employed-income calculator. Higher earners, directors, contractors, professionals receiving bonuses, applicants with investment income, and clients with income in foreign currencies can all require more detailed underwriting. We work with lenders and specialist underwriting teams that can assess complex financial profiles manually where appropriate. This is particularly useful when the required loan is substantial, the property is higher value, or the applicant's wealth and income are structured across several sources rather than a single basic salary.

Lake edged with reeds and trees near Stanford-le-Hope under a cloudy sky
More on high net worth mortgages
Open green space with trees and hedges in Stanford-le-Hope

Why work with a local mortgage broker

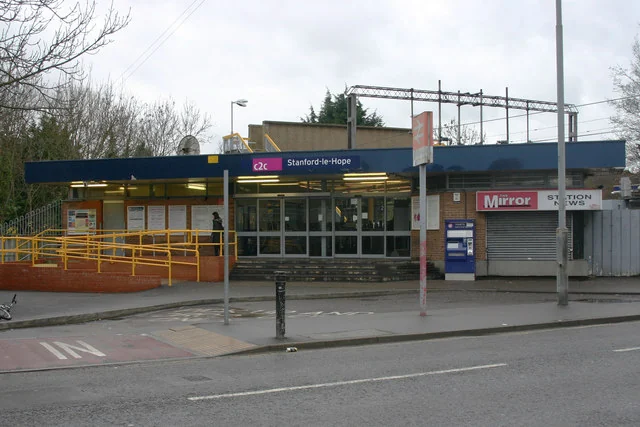
Stanford-le-Hope is a Thurrock town with its own c2c railway station and direct links towards London Fenchurch Street, while the A13 provides a major road connection towards London, the M25, Basildon, and Southend. The local property market covers a broad mix of flats, terraces, semi-detached family homes, detached properties, and older buildings around the historic centre, with Corringham and surrounding SS17 neighbourhoods adding further variety.

That variety can create property-specific questions during underwriting. Older or listed buildings around The Green and Church Hill may require closer attention to survey findings and alterations. Some lower-lying areas in and around Stanford-le-Hope also sit within the wider Thames Estuary flood-risk environment, so lenders, conveyancers, and insurers may consider flood-search information for an individual address. Leasehold flats can introduce another set of checks around remaining lease term, service charges, ground rent, and building management. We look at these issues early where they could affect lender choice.

We offer flexible consultations for clients in and around Stanford-le-Hope, including face-to-face appointments, telephone reviews, and video meetings. Our role extends beyond finding a rate: we help organise documents, explain lender requirements, respond to underwriting questions, and remain involved with the mortgage through to completion. That gives you one point of contact throughout the process rather than having to manage every lender query yourself.

How to apply

Getting mortgage advice in Stanford-le-Hope is straightforward and starts with a conversation about what you want to achieve. You may be preparing to buy in the next few months, checking whether a move is affordable, approaching the end of an existing fixed rate, or considering an investment property. Whatever the starting point, we use the first discussion to understand the objective, identify any obvious lender considerations, and explain the next steps.

1. First contact and affordability assessment

Call our team on 0333 339 0440 or send us a message online to arrange an initial, no-obligation consultation. This can take place in person, by telephone, or by video. We review your income, regular commitments, deposit or equity, credit position, and intended property plans. From there, we can give you a realistic indication of borrowing capacity and explain which documents are likely to be needed before an application.

2. Searching lenders and handling your application

Your dedicated adviser researches suitable lenders from our panel and compares the products that fit your circumstances. Once you are ready to proceed, we prepare the mortgage application, organise the supporting evidence, and submit the case to the chosen lender. We then deal with underwriting questions, valuation requirements, and any additional documentation requested while keeping you updated on progress.

3. Managing the chain through to completion

Receiving a mortgage offer is an important milestone, but the transaction still needs to move through the legal process. We remain available after offer, liaising where appropriate with your estate agent, conveyancer, and lender while the purchase or remortgage progresses. If an issue arises with paperwork, the mortgage offer, or completion timing, we help clarify what the lender needs so the financial side of the transaction remains on track.

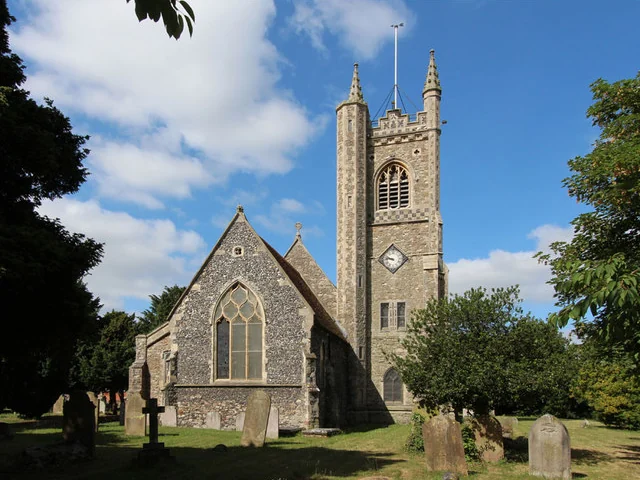
Flint and stone tower of St Margaret of Antioch Church, Stanford-le-Hope, above the churchyard

If you are planning to buy, move, remortgage, or invest in property in Stanford-le-Hope, speaking to a mortgage adviser before committing to a property or product can give you a clearer view of your options. We can assess affordability, explain how different lenders may approach your circumstances, and identify any property or income issues worth dealing with before an application is submitted.

Your initial consultation with AB Mortgages is free and there is no obligation to proceed. You will speak directly with a qualified mortgage adviser who can assess your borrowing position and discuss suitable mortgage routes. There may be a fee for mortgage advice. The precise amount depends on your circumstances and will always be confirmed before advice is given.

Take the first step today by calling our team on 0333 339 0440 to speak with an adviser.

Your home may be repossessed if you do not keep up repayments on your mortgage.

You may have to pay an early repayment charge to your existing lender if you remortgage.

Not all Buy to Let Mortgages are regulated by The Financial Conduct Authority.

Stanford-le-Hope

The map will load once you allow functional cookies.

What is the council tax authority and Band D rate for Stanford-le-Hope residents?

Stanford-le-Hope is within the Thurrock Council unitary authority. For the 2026/27 financial year, Thurrock's Band D council tax charge is £2,254.68 per year. The total includes the council element together with the relevant police and fire precepts. The amount actually payable for an individual home depends on its council tax band and any discounts, exemptions, or support that apply.

What are current average property prices in Stanford-le-Hope?

Homes in Stanford-le-Hope sold for an overall average of approximately £369,190 over the last year. Semi-detached properties made up a large part of the market and averaged around £394,439, while terraced homes averaged about £333,501 and flats around £195,712. These figures provide a useful local benchmark, but the value of an individual property can vary significantly by street, condition, size, tenure, and proximity to transport or amenities.

Figures correct as at September 2026, based on Rightmove sold price data (HM Land Registry) for the previous 12 months.

Which primary and secondary schools serve families living in Stanford-le-Hope?

Stanford-Le-Hope Primary School on Copland Road serves children from nursery through primary age. For secondary education, St Clere's School on Butts Lane is an 11-to-19 school, while Mossbourne Port Side Academy operates from Hassenbrook Road. Families in the wider SS17 area may also consider schools in nearby Corringham, including Mossbourne Fobbing Academy. Admissions and catchment arrangements can change, so buyers should always confirm the current position directly with the local authority and the relevant school.

How do Stanford-le-Hope residents connect to London by rail and road?

Stanford-le-Hope has its own c2c station with direct services to London Fenchurch Street. c2c currently lists an average direct journey time of around 51 minutes and an average service frequency of every 30 minutes, although individual train times vary. By road, Stanford-le-Hope has convenient access to the A13, providing connections west towards the M25 and London and east towards Basildon and Southend, making the town practical for commuters who use either rail or car.

What local landmarks and amenities define life in Stanford-le-Hope?

The town combines everyday shops and services with access to open space and the Thames-side landscape. The historic area around The Green and St Margaret of Antioch Church gives Stanford-le-Hope a recognisable older centre, while Thameside Nature Discovery Park at Mucking Wharf Road provides walking routes, wildlife habitats, a visitor centre, and views across the Thames Estuary. Nearby Stanford Warren Nature Reserve adds further reedbed and birdwatching habitat, giving residents access to significant green and waterside areas close to the town.

Are there specialist lender considerations for flood risk in Stanford-le-Hope?

Potentially, depending on the exact property. Stanford-le-Hope sits within the wider Thames Estuary area, and Environment Agency planning for nearby marshes identifies tidal, fluvial, and surface-water flood risks in parts of the locality. This does not mean every Stanford-le-Hope property is at significant flood risk. Mortgage lenders normally consider the specific address, conveyancing searches, valuation, and availability of suitable buildings insurance. Where a property has a recorded flood history or sits in a higher-risk area, we can identify lenders whose criteria are more appropriate before the application is submitted.

Are there different mortgage considerations for older or listed homes in Stanford-le-Hope?

Yes. Stanford-le-Hope has historic buildings around its older centre, including listed buildings in the vicinity of The Green and Church Hill. When buying an older, unusual, or listed property, a lender may pay closer attention to construction type, structural condition, previous alterations, and the valuer's comments. Your conveyancer will also investigate planning and listed-building consents where relevant. If a property falls outside standard construction or has unusual features, we can approach lenders that are comfortable assessing the property on its individual merits.

How do lenders evaluate self-employed directors drawing retained profits in Stanford-le-Hope?

Company directors are not always assessed purely on the salary and dividends they draw personally. Some mortgage lenders can consider a director's share of company profits, including retained profit, where the accounts and business performance support that approach. Other lenders use salary plus dividends or average income over a set period. We review the company accounts, ownership percentage, latest figures, and the amount you need to borrow before identifying lenders whose affordability method is suitable for your circumstances.

What is the typical deposit requirement for first-time buyers in Stanford-le-Hope?

The minimum deposit depends on the lender, mortgage product, property, and applicant, but some residential mortgages are available up to 95% loan-to-value, which means a 5% deposit may be possible for eligible buyers. Using Stanford-le-Hope's recent overall average sale price of about £369,190 as a simple illustration, 5% would be approximately £18,460 and 10% approximately £36,919. A larger deposit can reduce the loan-to-value and may provide access to a wider selection of products, but we assess what is realistic for your own budget rather than using the local average as a target.

When should I obtain an Agreement in Principle before viewing homes in Stanford-le-Hope?

It is sensible to arrange an Agreement in Principle before making serious offers on property, once you know your likely deposit and budget. An AIP indicates what a lender may be prepared to lend after an initial assessment and can help show an estate agent that you have considered the finance. It is not a mortgage offer, and the lender must still assess the full application and property.

Whatsapp svg icon