Black background with scattered dark grey outlined circles of varying sizes.

Trusted by our
leading partners:

Halifax logo with white text and geometric shapes on a blue background.NatWest logo with three red cubes forming a triangle above the white text on a purple background.Nationwide logo with red abstract house icon on dark blue background.HSBC logo with black letters and a red and white hexagon symbol above.Virgin Money logo with red text on a black background.Barclays bank logo with a white eagle icon above the word BARCLAYS on a blue background.White bold letters spelling GEN H with a red house-shaped icon under the E on a black background.Logo for The Mortgage Works with orange text and a star symbol.BM Solutions logo with text from Birmingham Midshires.Aldermore logo with a yellow dot replacing the letter o.Kensington brand logo with stylized white letter K on black background.Paragon text logo with a green and black abstract bird shape above the letter g.Bluestone logo with blue and gray text and a blue sphere at the end.Buildloan logo with a stylized roof over the letter 'l' in the word loan.Coutts logo with stylized text and three crowns icon separated by a vertical line.

First-time buyers

Buying your first property in Leigh-on-Sea is an exciting financial milestone, but handling deposit requirements, Agreement in Principle documents, and legal checks can feel overwhelming. We take the stress out of entering the Leigh market by calculating your precise borrowing capacity 3 to 6 months before you begin viewing properties, preventing you from wasting time on homes outside your budget. We guide you through available deposit boost options, Joint Borrower Sole Proprietor (JBSP) agreements, and family gifted deposit rules. Once you find the right Leigh property, we handle the application process through to completion.

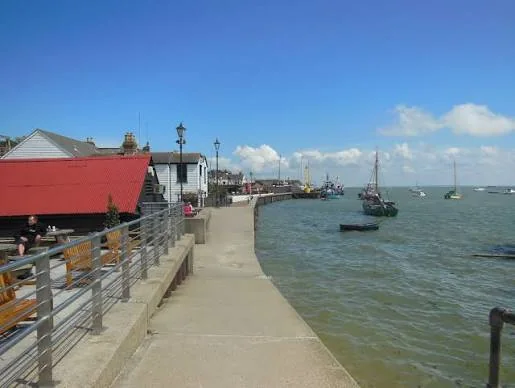
Waterfront path in Old Leigh with moored boats on the estuary
More on first-time buyer mortgages

Moving home

Relocating within Leigh-on-Sea or moving into the area requires managing an outgoing sale and an incoming purchase simultaneously, making timing and organisation vital. We evaluate your current mortgage deal to decide whether porting your existing interest rate to your new Leigh property makes financial sense compared to switching to a new lender, taking into account any potential Early Repayment Charges (ERCs). Our team calculates your total moving expenses, establishes your maximum purchasing budget, and keeps conveyancers on schedule to avoid chain delays.

Waterfront path in Old Leigh with moored boats on the estuary
More on moving home mortgages

Remortgaging and rate switches

Remaining on your current lender's Standard Variable Rate (SVR) after a fixed product finishes can add hundreds of pounds to your monthly household budget. For homeowners across Leigh-on-Sea, we recommend starting the remortgage process 6 months prior to your fixed rate expiration date. This allows us to lock in a competitive benchmark rate early as protection against interest rate increases, while retaining full flexibility to switch to a lower rate if market conditions improve before completion. We compare your current lender's retention offers against the wider market to ensure your home remains cost-effective.

Waterfront path in Old Leigh with moored boats on the estuary
More on remortgaging

Self-employed mortgages

If you run a local business, work as a sole trader, or trade as a company director in Leigh-on-Sea, high street lenders often apply rigid automated rules. Lenders assess self-employed income in fundamentally different ways: some average two full years of trading accounts, others assess solely the latest trading year, and select lenders calculate affordability using your salary plus your share of retained business profits. As local mortgage advisers, we know which lenders evaluate your type of trading setup favourably, ensuring your application reaches underwriters who assess your accounts accurately.

Waterfront path in Old Leigh with moored boats on the estuary
More on self-employed mortgages

Buy-to-let and portfolio landlords

Navigating the Leigh private rental market requires specialist mortgage advice, particularly with shifting regulatory standards and strict rental yield stress testing. Whether you are purchasing your first buy-to-let flat near the Broadway or expanding an established residential portfolio across Leigh-on-Sea, we help you evaluate borrowing as an individual versus using a Limited Company / Special Purpose Vehicle (SPV) structure for tax efficiency. For landlords with four or more mortgaged properties, we package your entire portfolio professionally for specialist lenders who underwrite your holdings as a commercial business.

Waterfront path in Old Leigh with moored boats on the estuary
More on buy-to-let mortgages

Adverse and bad credit mortgages

A past credit issue does not automatically mean you cannot buy or remortgage a home in Leigh-on-Sea. Lenders judge historical defaults, old CCJs, missed credit payments, or completed debt management plans in vastly different ways depending on their recency, value, and context. Rather than risking a credit decline on the high street, our team examines your full credit report upfront, matches you with adverse-credit lenders who review cases manually, and gives you clear advice on whether applying now or waiting a short period will secure a cheaper rate.

Waterfront path in Old Leigh with moored boats on the estuary
More on adverse credit mortgages

High net worth and complex income mortgages

Standard automated affordability calculators frequently fail high earners looking to purchase higher-value properties in premium locations like the Marine Estate or Grand Parade. If your remuneration includes variable performance bonuses, complex dividend distributions, foreign currency income, or wealth held in assets rather than traditional salary, high street algorithms often cannot read your profile accurately. We deal directly with specialist lenders and bespoke underwriting desks that manually assess complex financial profiles, constructing custom high-value mortgage structures tailored to your wider financial goals.

Waterfront path in Old Leigh with moored boats on the estuary
More on high net worth mortgages
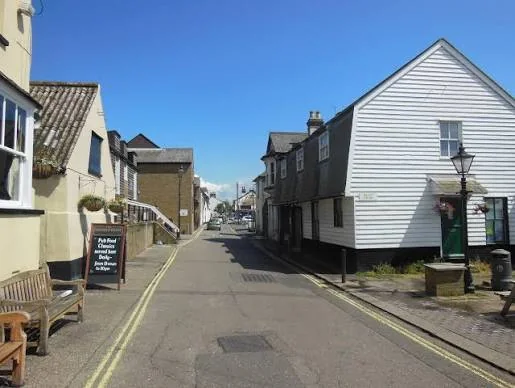
Narrow street of white weatherboarded and period buildings in Old Leigh

Why work with a local mortgage broker

Leigh-on-Sea is two places in one. Old Leigh sits below the cliff by the estuary, with the cockle sheds, historic pubs and conservation area rules, while the Broadway, Leigh Road and the avenues above it are where most people live. Leigh has its own Town Council, which adds a precept to the Southend council tax bill.

Many houses on the avenues have loft conversions and extensions, and lenders will want building control sign-off for them. In Old Leigh, listed status and conservation rules bring their own survey and planning questions. We check the paperwork before an application goes in, so a missing certificate does not stall the purchase.

We offer full flexibility for client consultations, welcoming you for face-to-face meetings, or conducting phone reviews and video calls to suit your routine. From checking your initial bank statements to communicating with Leigh estate agents and solicitors, our team handles the behind-the-scenes administration so your transaction moves forward smoothly.

How to apply

Getting expert mortgage advice in Leigh-on-Sea is straightforward, transparent, and completely tailored to your schedule. Whether you have a quick question about your deposit or need a full review of your borrowing potential, reaching out carries zero obligation. We guide you through the process from your very first conversation right through to completion day in three clear steps:

1. First contact and affordability assessment

Reach out by calling our local team on 0333 339 0440 or sending us a message online. We will arrange an initial, no-obligation consultation at a time that suits you: in person, over the phone, or via video link. During this conversation, we review your financial picture, assess what you can realistically borrow, and confirm how much deposit or equity you have available.

2. Searching lenders and handling your application

Your dedicated adviser searches across an extensive panel of UK lenders to locate the most suitable mortgage rate for your circumstances. Once you are happy to move forward, we prepare and submit your full application. We gather your paperwork, submit income evidence, and deal directly with lender underwriters to ensure your Agreement in Principle moves smoothly to a formal mortgage offer.

3. Managing the chain through to completion

Our work does not end when your mortgage offer is approved. We stay actively involved right up until completion day, communicating with local Leigh estate agents, surveyors, and conveyancers on your behalf. We proactively solve administrative hurdles or chain delays so that your funds reach your solicitor smoothly on completion day.

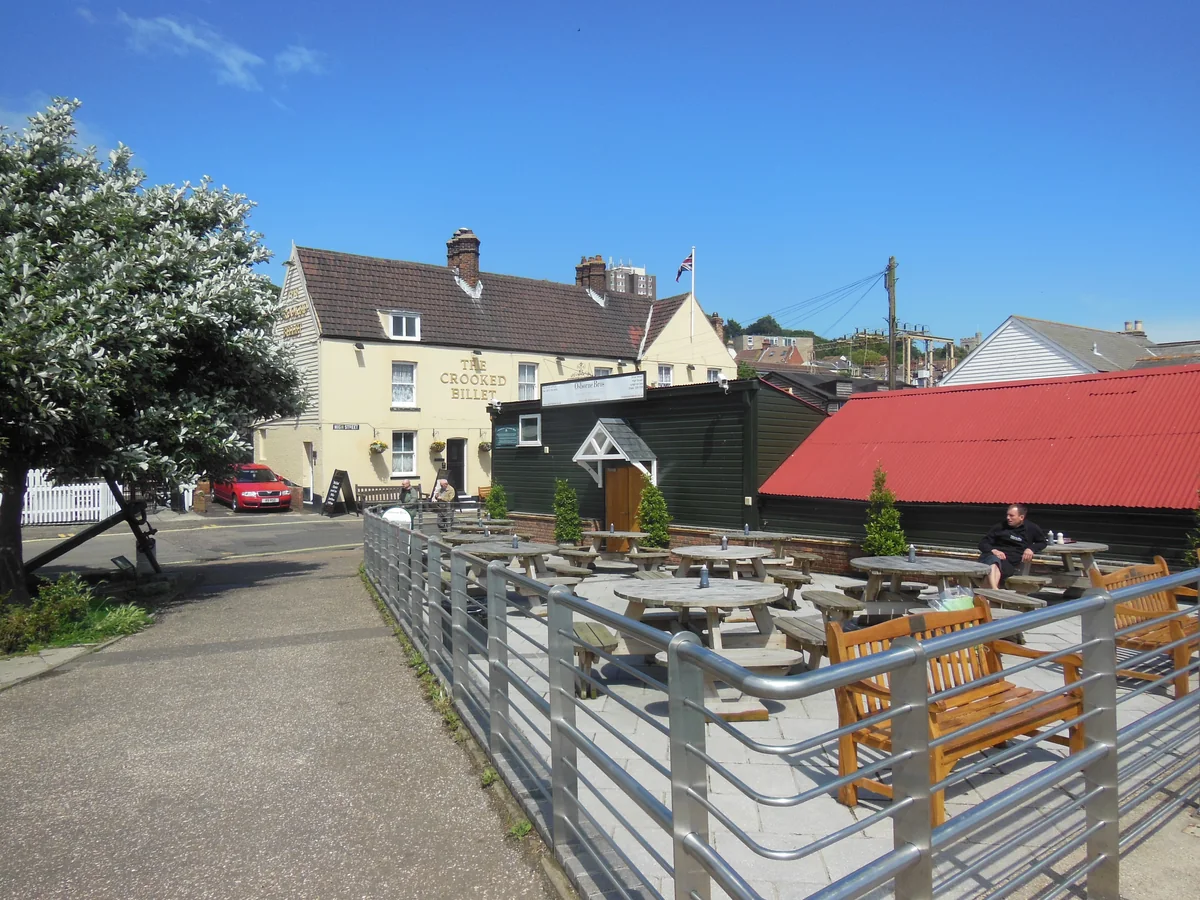
The Crooked Billet pub and outdoor seating on the High Street in Old Leigh

If you are ready to take your next step on the Leigh property ladder, protect your household against rising interest rates, or release equity from your current home, speaking to an adviser before committing to a deal is invaluable.

When you contact AB Mortgages, your initial consultation is completely free with no obligation to proceed. You will speak directly to a qualified local adviser who will calculate your exact borrowing power and guide you towards suitable mortgage options for your budget. There may be a fee for mortgage advice. The precise amount depends on your circumstances and will be agreed upon before proceeding.

Take the first step today by calling our team on 0333 339 0440 to speak with an adviser.

Your home may be repossessed if you do not keep up repayments on your mortgage.

You may have to pay an early repayment charge to your existing lender if you remortgage.

Not all Buy to Let Mortgages are regulated by The Financial Conduct Authority.

Leigh-on-Sea

The map will load once you allow functional cookies.

What is the council tax authority and Band D rate for Leigh-on-Sea?

Leigh-on-Sea falls under Southend-on-Sea City Council, with properties in the town paying an additional precept to Leigh-on-Sea Town Council. For the 2026/27 financial year, the Southend Band D charge of £2,256.30 combines with the Town Council precept of £59.39, bringing the total Band D charge in Leigh-on-Sea to £2,315.69.

What are average property prices in Leigh-on-Sea and premium enclaves?

Homes in Leigh-on-Sea sold for an average of around £444,000 over the last year, among the higher prices in South Essex. Flats averaged around £270,000, semi-detached houses around £489,000 and detached houses around £583,000, with larger homes on the Marine Estate and along Grand Parade often selling well above that.

Figures correct as at September 2026, based on Rightmove sold price data (HM Land Registry) for the previous 12 months.

Which primary and secondary schools serve the Leigh-on-Sea community?

Leigh-on-Sea features highly regarded primary schools including West Leigh Junior School and Leigh North Street Primary. Secondary pupils fall within catchments for Belfairs Academy or nearby Southend and Westcliff grammar schools, accessible via short local transport routes.

How fast is the c2c train service from Leigh-on-Sea station to Fenchurch Street?

Leigh-on-Sea Rail Station operates on the c2c line, offering peak direct services into London Fenchurch Street in as little as 45 to 50 minutes. The station sits at the bottom of Belton Way, serving commuters across Leigh and Old Leigh.

What features make Leigh Broadway and Old Leigh major lifestyle drivers for buyers?

Leigh-on-Sea combines seaside character with a vibrant high street environment along Leigh Broadway, Leigh Road, and Rectory Grove, packed with independent boutiques, cafes, and restaurants. Below the hill lies Old Leigh, famous for its cockle sheds, historic pubs, yacht clubs, and estuary views.

Are there special mortgage rules for historic property or conservation areas in Leigh?

Yes. Properties located within the Leigh Conservation Area or historic cottages in Old Leigh often involve listed building status, non-standard timber framing, or strict planning constraints. We match buyers of character homes with lenders who evaluate heritage stock pragmatically without demanding excessive deposit margins.

How do lenders evaluate structural alterations or loft conversions on Leigh avenues?

Many character houses on the Leigh avenues have undergone extensive loft conversions or open-plan ground floor extensions. Mortgage surveyors verify that structural alterations hold correct local authority building control sign-offs. If documentation is missing, we work with lenders who accept indemnity policies to keep your mortgage application on track.

Can I secure a mortgage in Leigh if my deposit is being boosted by family?

Yes. Given higher property values in Leigh-on-Sea, gifted deposits from parents or family members are common. Lenders require a formal gifted deposit letter confirming the funds are a non-repayable gift, alongside standard anti-money laundering identification checks on the donor.

What deposit level do I need to buy an investment property in Leigh-on-Sea?

Buy-to-let lenders in Leigh typically require a minimum 25% deposit. Due to premium purchase prices around Leigh Broadway, rental yield stress tests are stricter, meaning higher initial equity often helps secure lower interest rate deals and meet lender affordability rules.

When should I get an Agreement in Principle before viewing homes in Leigh?

Due to competitive demand among buyers in Leigh-on-Sea, local estate agents frequently ask for an Agreement in Principle (AIP) before arranging viewings or submitting formal offers. We issue AIPs promptly after verifying your income documents, giving you an immediate advantage in the local market.

Whatsapp svg icon