Black background with scattered dark grey outlined circles of varying sizes.

Trusted by our
leading partners:

Halifax logo with white text and geometric shapes on a blue background.NatWest logo with three red cubes forming a triangle above the white text on a purple background.Nationwide logo with red abstract house icon on dark blue background.HSBC logo with black letters and a red and white hexagon symbol above.Virgin Money logo with red text on a black background.Barclays bank logo with a white eagle icon above the word BARCLAYS on a blue background.White bold letters spelling GEN H with a red house-shaped icon under the E on a black background.Logo for The Mortgage Works with orange text and a star symbol.BM Solutions logo with text from Birmingham Midshires.Aldermore logo with a yellow dot replacing the letter o.Kensington brand logo with stylized white letter K on black background.Paragon text logo with a green and black abstract bird shape above the letter g.Bluestone logo with blue and gray text and a blue sphere at the end.Buildloan logo with a stylized roof over the letter 'l' in the word loan.Coutts logo with stylized text and three crowns icon separated by a vertical line.

First-time buyers

Taking your initial step onto the Castle Point property ladder is a major financial milestone. We help first-time buyers evaluate their exact borrowing limit 3 to 6 months before making offers, avoiding wasted viewings on unsuitable properties. We explain every funding route available, including deposit boost schemes, Joint Borrower Sole Proprietor (JBSP) agreements, and gifted deposit declarations, managing the entire application through to key handover.

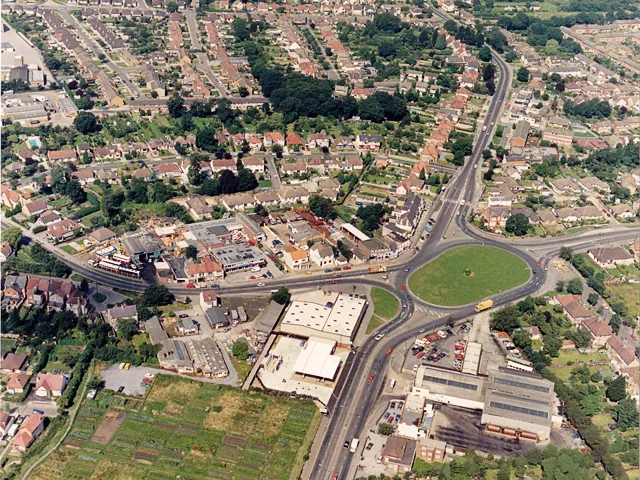
Aerial view of homes, shops and a large roundabout in Castle Point
More on first-time buyer mortgages

Moving home

Upgrading or downsizing within Castle Point requires balancing an outgoing sale with an incoming purchase. We evaluate whether "porting" your current mortgage rate is financially advantageous compared to taking a fresh deal, factoring in potential Early Repayment Charges (ERCs). Our advisers calculate total moving costs, determine your max purchase price, and keep conveyancers on schedule to prevent chain delays.

Aerial view of homes, shops and a large roundabout in Castle Point
More on moving home mortgages

Remortgaging and rate switches

Failing to act before a fixed mortgage rate expires risks auto-enrolling onto a lender's expensive Standard Variable Rate (SVR). For Castle Point homeowners, we initiate remortgage reviews 6 months prior to product expiration. This enables us to lock in a competitive rate early as a safety net against rate rises, while retaining flexibility to switch if lower rates emerge before completion. We compare your current lender's retention deals against the broader market.

Aerial view of homes, shops and a large roundabout in Castle Point
More on remortgaging

Self-employed mortgages

Business owners, sole traders, and company directors across Castle Point often face rigid automated checks from traditional high street lenders. Lenders assess self-employed income in fundamentally different ways: some average two years of accounts, others take the latest year, and select specialist lenders calculate affordability using salary plus retained company profits. We know which lenders assess your type of business the way you'd want it assessed, so your accounts go to the ones most likely to lend without weeks of back and forth.

Aerial view of homes, shops and a large roundabout in Castle Point
More on self-employed mortgages

Buy-to-let and portfolio landlords

Whether you are buying an individual buy-to-let unit or managing an established residential portfolio, we structure borrowing personally or via a Special Purpose Vehicle (SPV) Limited Company for tax efficiency. For portfolio landlords holding four or more mortgaged properties, we package your commercial assets for specialist manual underwriting.

Aerial view of homes, shops and a large roundabout in Castle Point
More on buy-to-let mortgages

Adverse and bad credit mortgages

A past credit hiccup does not automatically block your property plans in Castle Point. Lenders treat historical defaults, old County Court Judgments (CCJs), missed payments, or completed debt management plans differently depending on their recency and severity. We examine your full credit report, matching you with adverse-credit lenders who review cases manually and advising whether a brief waiting period would unlock significantly cheaper rates.

Aerial view of homes, shops and a large roundabout in Castle Point
More on adverse credit mortgages

High net worth and complex income mortgages

Higher-value properties across Castle Point often involve buyers with non-standard income structures. High street banks often can't read income properly at all when it comes from performance bonuses, profit shares, multi-currency revenue, or wealth held in assets rather than salary. We work directly with specialist banks and bespoke underwriting desks that manually assess complex financial profiles to build custom, high-value mortgage structures.

Aerial view of homes, shops and a large roundabout in Castle Point
More on high net worth mortgages
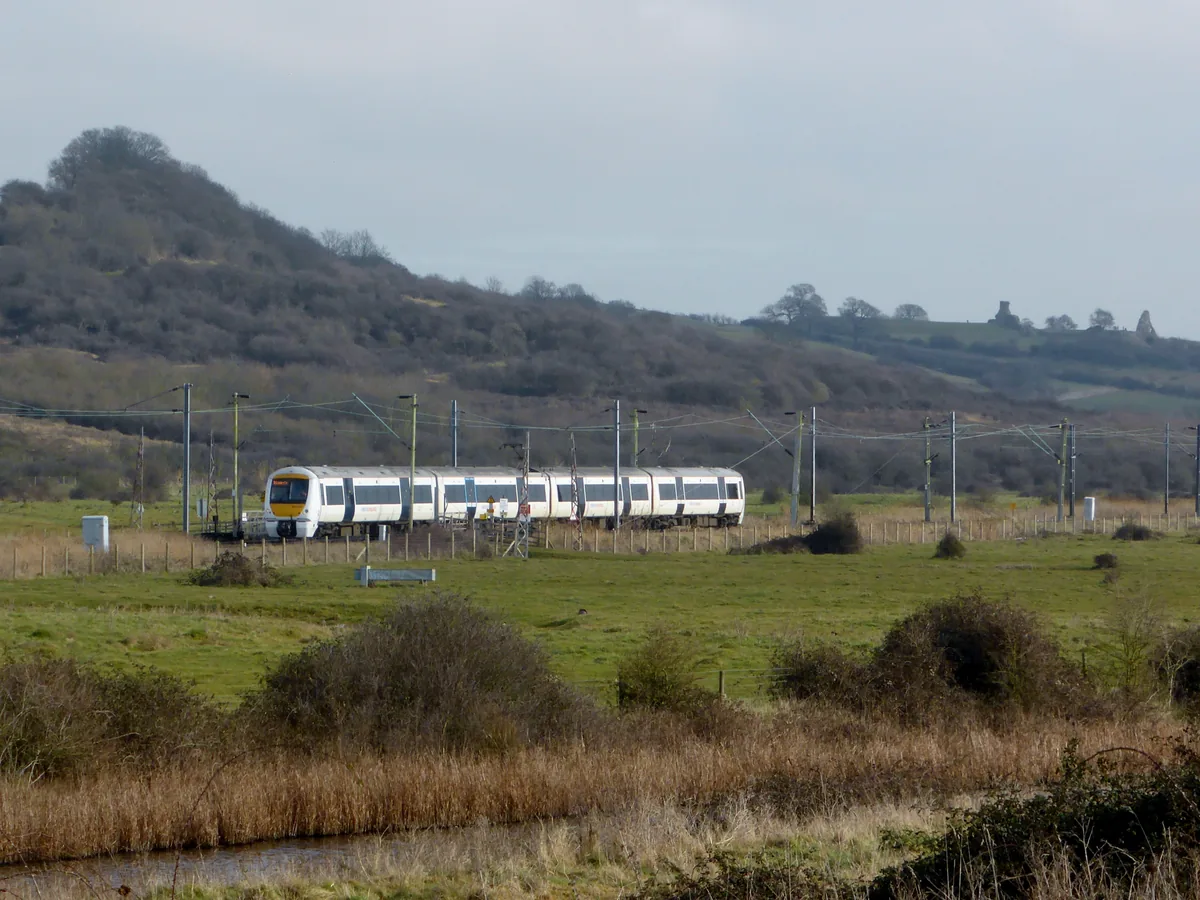
c2c train crossing the marshes below Hadleigh Downs, with the castle ruins on the ridge

Why work with a local mortgage broker

Castle Point is two quite different markets. On the mainland, Benfleet, Hadleigh and Thundersley sit on higher ground, with the South Benfleet and Florence Gardens conservation areas bringing extra planning controls to two small pockets. Canvey Island sits behind its sea wall and flood defences, pays a Town Council precept on top of the borough council tax, and has more bungalows and chalets than the mainland.

Lenders ask different questions on each side of the creek. On Canvey it is flood risk, construction type and insurance. On the mainland it is more often the age of the property, past alterations or conservation area rules. We check the property against lender criteria before we apply, rather than finding out at valuation.

We accommodate your routine with in-person meetings at our local office, direct phone calls, or video consultations. From reviewing initial bank statements to communicating with local Castle Point estate agents and solicitors, we handle all administrative tasks so your transaction progresses without friction.

How to apply

Getting expert mortgage advice in Castle Point is simple, transparent, and completely tailored to your circumstances. From initial affordability checks to final completion, we guide you through three clear steps:

1. First contact and affordability assessment

Contact our team on 0333 339 0440 or complete an online enquiry. We will schedule a free, no-obligation consultation, in person, over the phone, or via video call. During this chat, we analyse your financial position, establish realistic borrowing parameters, and confirm your available deposit or equity.

2. Searching lenders and handling your application

Your dedicated adviser searches across an extensive panel of UK lenders to find the right mortgage product for your budget. Once approved by you, we prepare and submit your full application, managing document collation and underwriting queries to turn an Agreement in Principle into a formal mortgage offer.

3. Managing the chain through to completion

Our work continues after your mortgage offer is issued. We maintain active communication with Castle Point estate agents, surveyors, and conveyancers, resolving potential legal or administrative bottlenecks so funds are transferred smoothly on completion day.

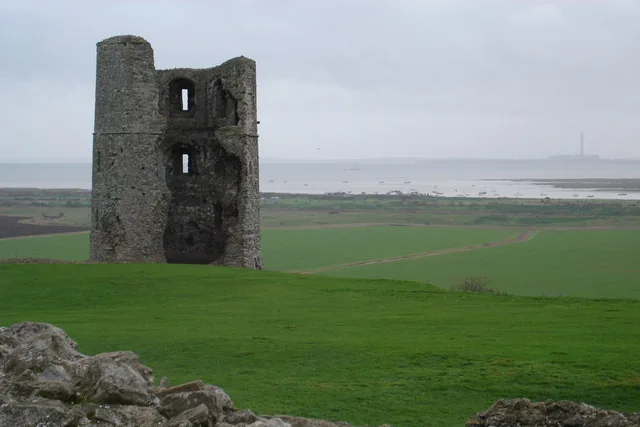
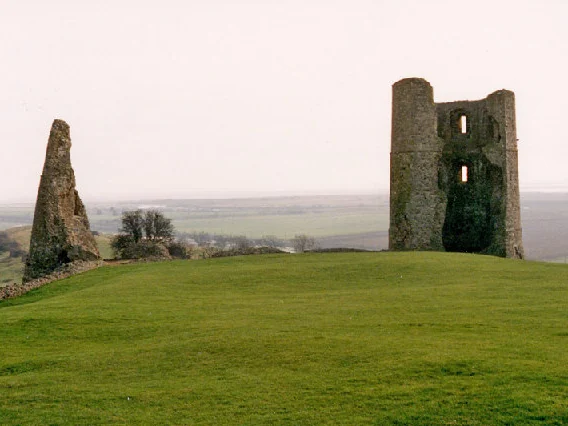
Ruined towers of Hadleigh Castle on the hillside overlooking the estuary

If you are ready to take your next step in the Castle Point property market, protect your household against rate changes, or release equity from an existing home, it's worth speaking to an adviser before you commit to anything.

When you contact AB Mortgages, your initial discussion carries zero cost and no obligation. You will speak directly with a qualified local adviser who will calculate your borrowing limits and outline suitable mortgage options. There may be a fee for mortgage advice; the precise amount depends on your circumstances and will be agreed upon before proceeding.

Take the first step today by calling our Castle Point team on 0333 339 0440 to speak with an adviser.

Your home may be repossessed if you do not keep up repayments on your mortgage.

You may have to pay an early repayment charge to your existing lender if you remortgage.

Not all Buy to Let Mortgages are regulated by The Financial Conduct Authority.

Castle Point

The map will load once you allow functional cookies.

What borough council covers Castle Point, and what does that mean for council tax?

The entire area is governed by Castle Point Borough Council. For the 2026/27 financial year, the baseline Band D council tax rate across Castle Point is £2,308.59. Properties located on Canvey Island pay an additional local parish precept (bringing Band D to roughly £2,334.51), while mainland areas like Benfleet, Hadleigh, and Thundersley pay the core borough rate. Total bills include precepts collected for Essex County Council, Essex Police, and Essex Fire & Rescue.

Figures correct as at September 2026. Council tax rates are set each March for the year starting 1 April, so check the current rate with Castle Point Borough Council before you budget on it.

Which secondary schools serve the Castle Point area?

Castle Point features several major secondary academies, including The Appleton School in Benfleet, The King John School in Thundersley (which includes an 11 to 18 sixth form), The Deanes School in Thundersley, and Castle View School and Cornelius Vermuyden School on Canvey Island. Admission policies are largely geography- and catchment-based.

What bus links connect Castle Point communities?

Bus transport across Castle Point is mainly run by First Essex. The 22 runs from Canvey through Benfleet station to Pitsea and Basildon, the 27 runs from Canvey through Benfleet and Hadleigh to Rayleigh and Hullbridge, and the hourly 21 links Canvey with Leigh and Southend. The 28 runs along the A13 through Tarpots and Hadleigh into Southend every 7 to 9 minutes on weekdays.

What is the average house price across Castle Point?

Property values vary across Castle Point. ONS figures put the average price across the borough at £357,000 in July 2026, with detached homes averaging £477,000, semi-detached £350,000, terraced £287,000 and flats £164,000. Prices run higher in Thundersley and Benfleet than on Canvey Island, where homes sold for an average of around £338,000 over the last year.

Figures correct as at September 2026, based on ONS House Price Index figures for July 2026 (provisional) and Rightmove sold price data.

Is Castle Point a practical area for families with children?

Yes. Castle Point offers extensive green space and waterfront parkland, including Hadleigh Castle Country Park, Benfleet Downs, and the Canvey Island seafront. Local amenities include Runnymede Swimming Pool, local leisure centres, public libraries, and quick road access via the A13 and A127 towards larger shopping hubs in Southend and Lakeside.

Which train operator serves rail stations in Castle Point?

Rail infrastructure in Castle Point is operated exclusively by c2c on the London, Tilbury and Southend line. Benfleet Station serves as the principal interchange for mainland Castle Point and Canvey Island commuters, delivering direct connections into London Fenchurch Street in approximately 38 to 45 minutes.

How far in advance should I speak to a Castle Point mortgage broker before buying?

We recommend consulting a mortgage broker 3 to 6 months before starting active property viewings. Early preparation allows us to optimise your credit footprint, review bank statements, and issue an Agreement in Principle (AIP) that local Castle Point estate agents require before submitting offers.

Do I have to use the in-house broker recommended by a Castle Point estate agent?

No. You are under no legal obligation to use an estate agent's internal mortgage adviser. Estate agents must submit all formal offers to sellers regardless of who handles your mortgage. Using a local mortgage broker ensures your advice is impartial and drawn from a wider panel of lenders.

When should I begin remortgaging my Castle Point property?

You should initiate the remortgage process 6 months before your current fixed rate deal ends. Securing a replacement product early protects you against market rate increases while leaving you free to switch if lower rates become available prior to your completion date.

Are there special mortgage rules for older homes in Castle Point?

Yes. Historical properties in the South Benfleet and Florence Gardens (Hadleigh) conservation areas, or older timber-framed structures require specialised underwriting. Lenders inspect construction types, flood risk profiles (for low-lying areas), and proximity to estuary channels. We match these properties with lenders comfortable with non-standard construction.

Whatsapp svg icon